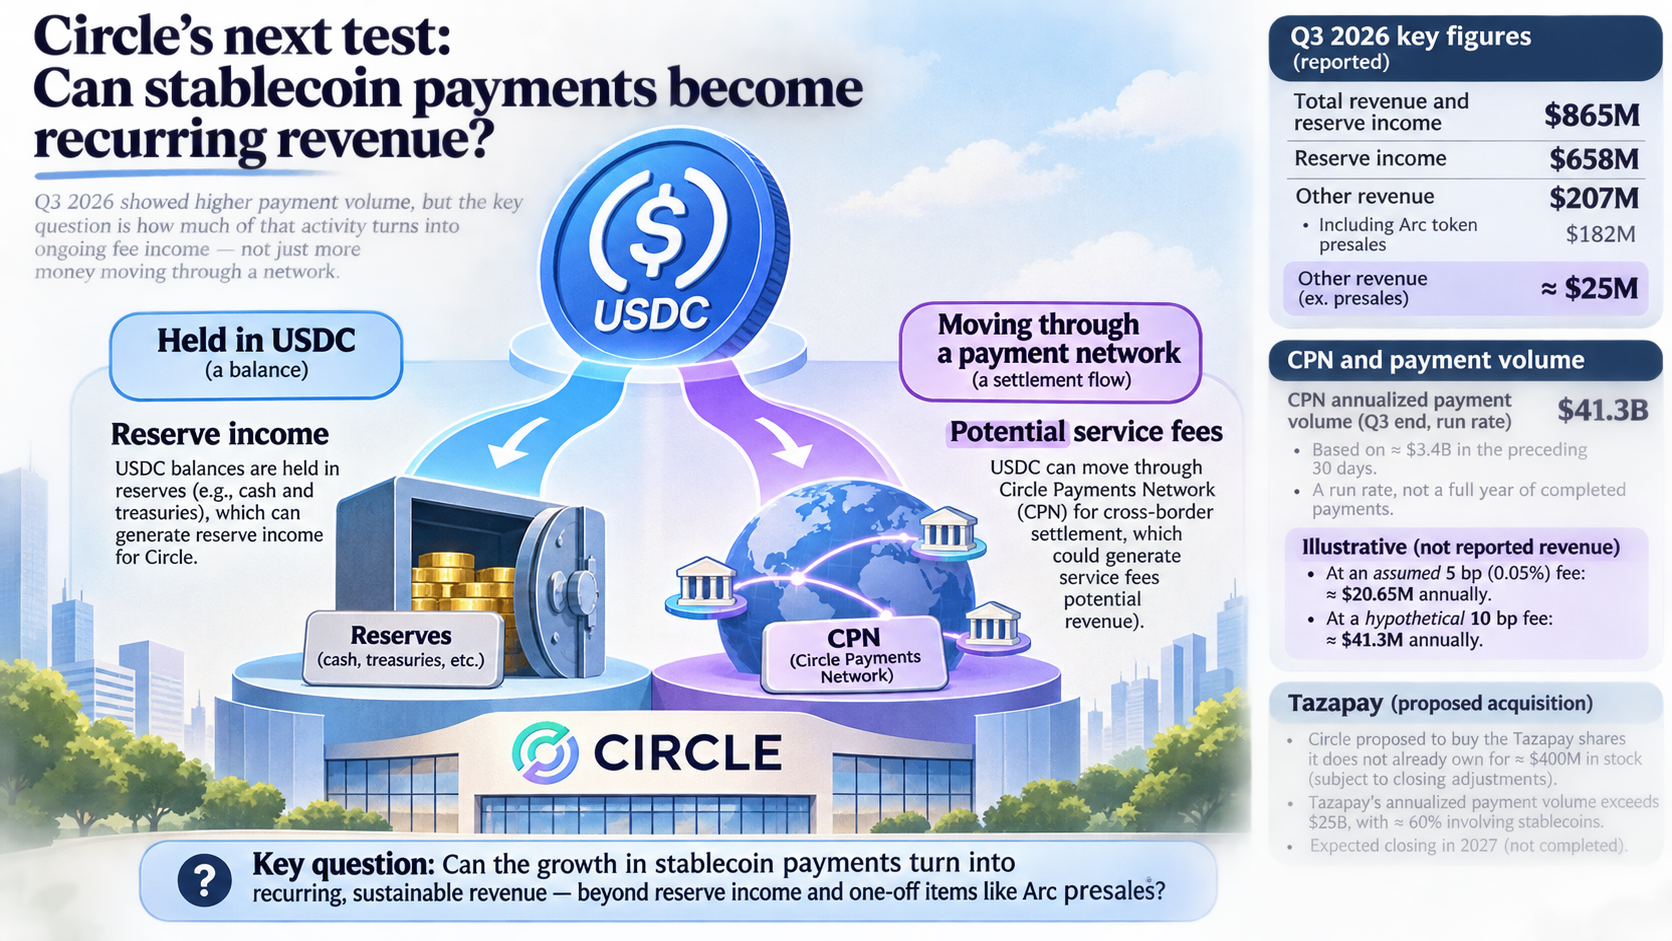
In a November 17, 2026 analysis of Circle’s third-quarter results, the central question was whether growth in stablecoin payments could become recurring revenue—not just move more money through a network.
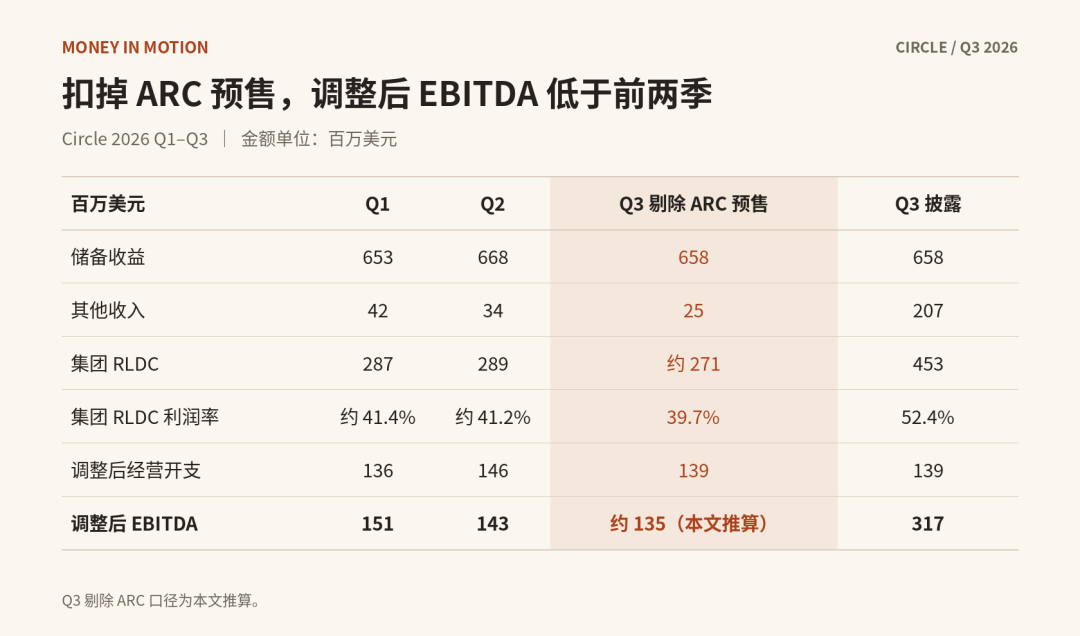
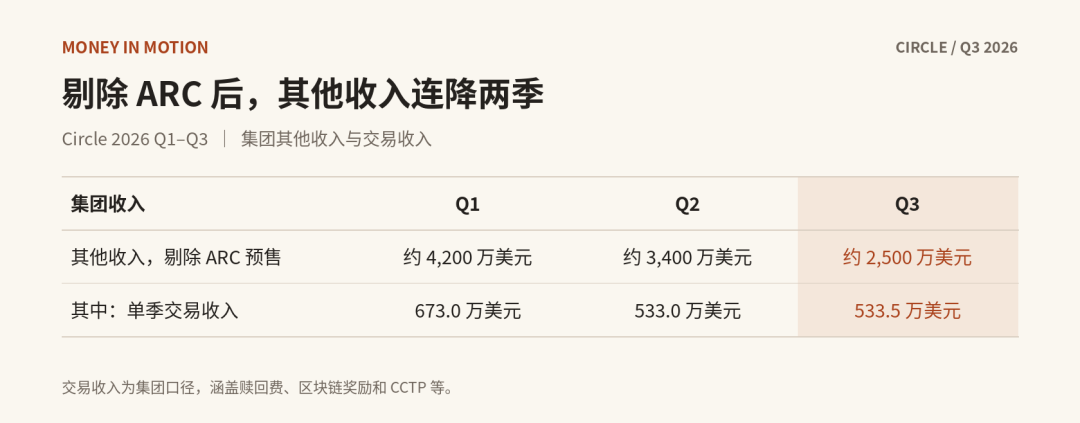
Circle reported $865 million in Q3 2026 revenue and reserve income, including $658 million in reserve income and $207 million in other revenue. About $182 million of that other revenue came from Arc token presales. Subtracting the presale amount leaves roughly $25 million in other revenue for the quarter. The analysis also notes that simply subtracting the presale revenue from Circle’s reported $317 million adjusted EBITDA gives a rough $135 million figure; that subtraction is not a separately reported company metric.
More payment volume, but how much fee income?
Circle Payments Network (CPN) connects financial institutions for stablecoin-based cross-border settlement. Its annualized payment volume reached $41.3 billion at the end of Q3, calculated from roughly $3.4 billion in volume over the preceding 30 days. That is a run rate, not a full year of completed payments.
At an assumed fee of 5 basis points (0.05%), maintaining that run rate for a year would imply about $20.65 million in revenue. It does not establish what CPN actually charged or earned. Circle reports transaction revenue at the group level, alongside items such as redemption fees, blockchain rewards and CCTP-related infrastructure revenue, so CPN’s fee contribution cannot be isolated from the figures cited in the analysis.
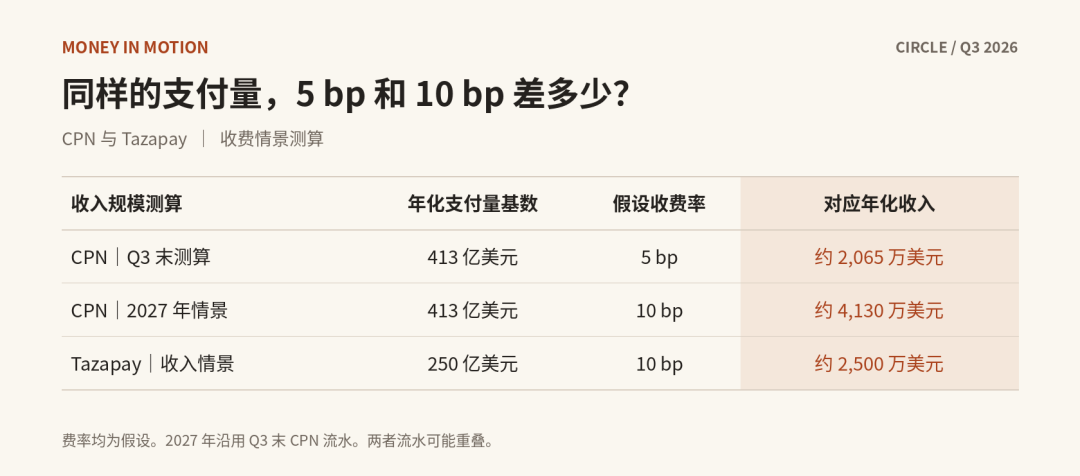
Circle also proposed buying the Tazapay shares it did not already own for approximately $400 million in stock, subject to closing adjustments. Tazapay, already a CPN design partner, had annualized payment volume exceeding $25 billion, with about 60% involving stablecoins. The proposed purchase could bring customer relationships and local payout capabilities closer to Circle, but it was not a completed acquisition. The analysis expected closing in 2027.
Using the same Q3-end CPN run rate, a hypothetical 10-basis-point fee would imply about $41.3 million annually. That is a scenario, not reported revenue or a confirmed Tazapay fee. CPN and Tazapay volumes may overlap, so the two estimates cannot be added together.
Why settlement volume is not the whole earnings story
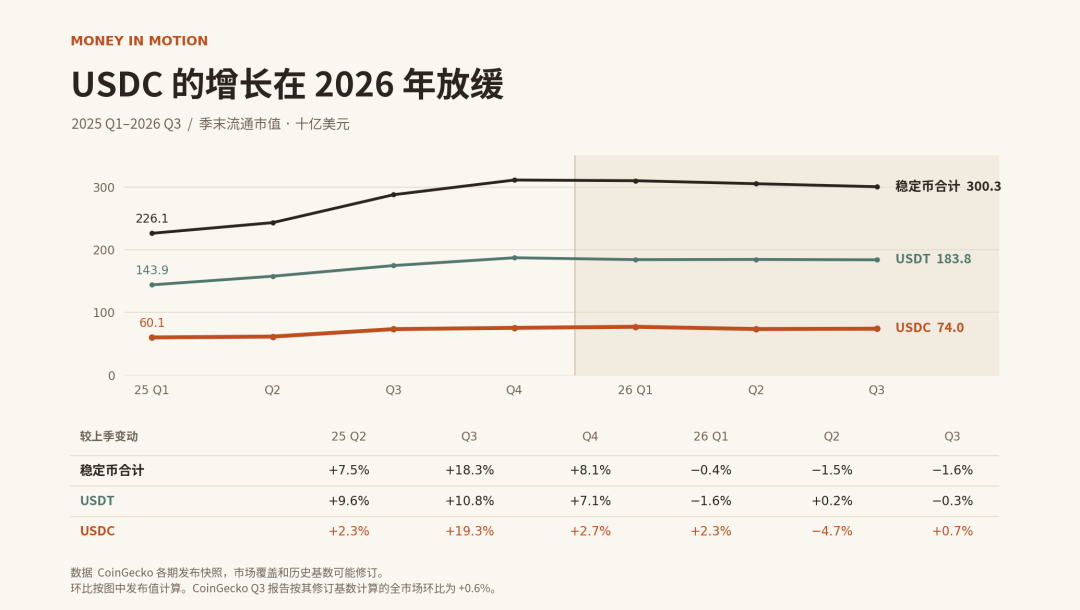
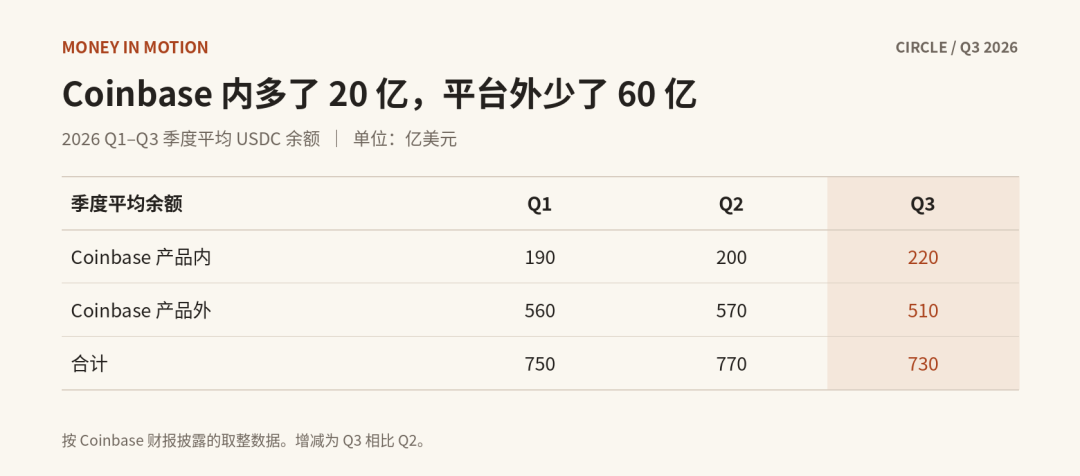
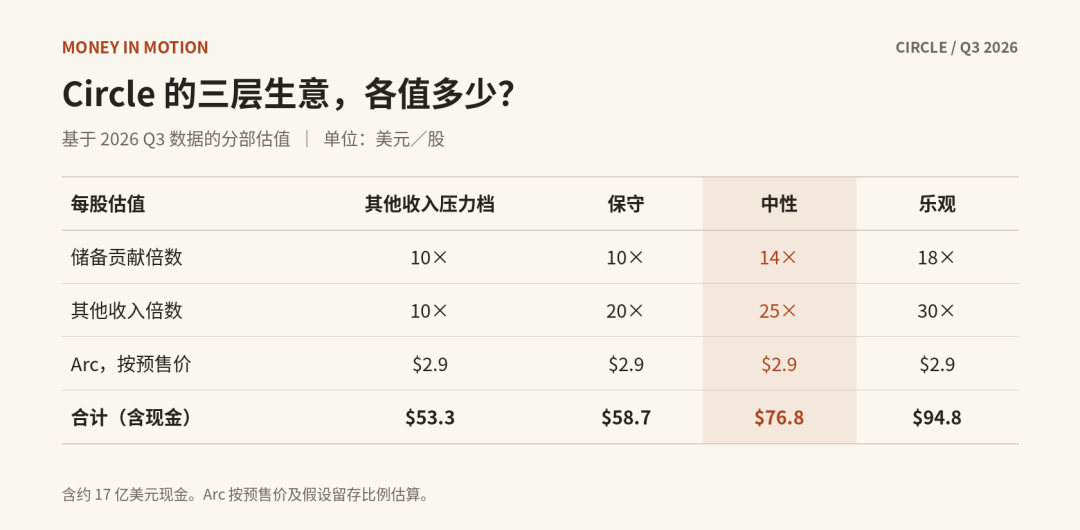
Circle’s reserve income fell from $668 million in Q2 to $658 million in Q3. Its average USDC circulation for the quarter was $73.3 billion, down 4% quarter over quarter. According to the analysis, after related distribution and transaction costs, Circle retained $37.80 for every $100 of reserve income, versus $38.60 in Q2. It reports that Circle’s CFO primarily attributed the decline to the Hyperliquid partnership operating for a full quarter, with associated USDC balances held on Coinbase. The renewed Binance distribution terms would not operate for a full quarter until Q4.
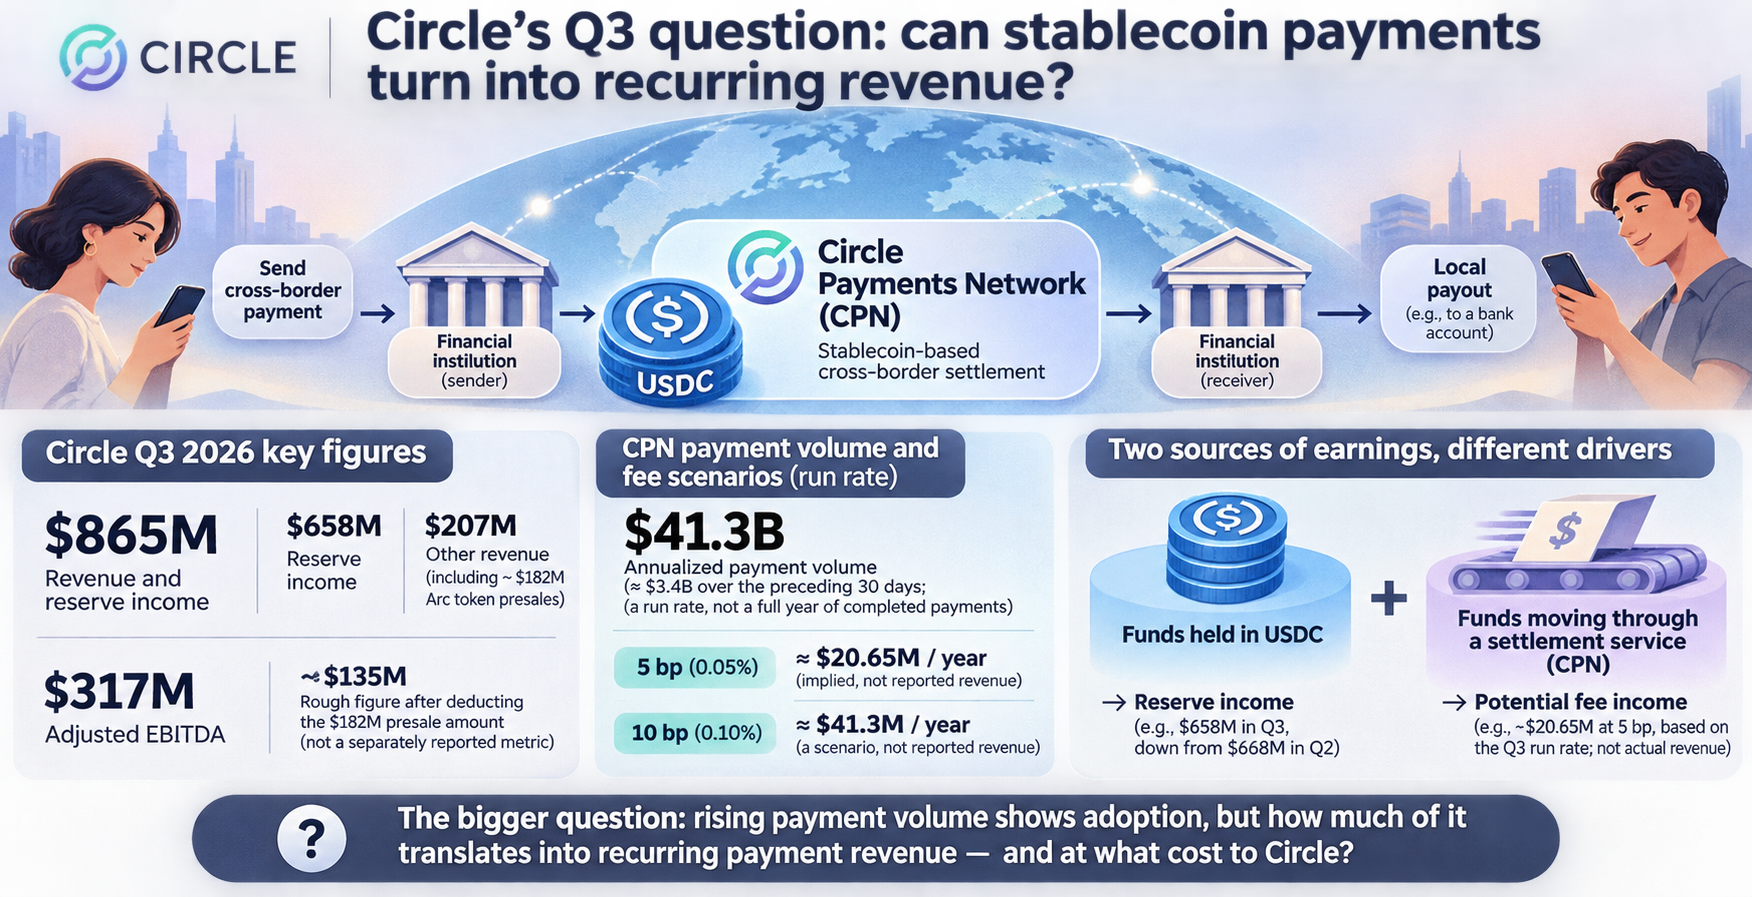
For a user or business sending a cross-border payment, the distinction is between funds held in USDC, which can support reserve income, and funds moving through a settlement service, which might generate a fee even if they are soon converted to local currency. Q3 showed rising CPN volume, but the disclosed figures did not yet show how much of that activity became recurring payment revenue or what it cost Circle to provide it.